31904587 | Burst Water Main © Nigel Spooner | Dreamstime.com
More than forty years on, the water industry still hasn’t sorted out its approach to managing ageing assets. Read UK water expert Jo Parker on a plan to change this, starting with assets in England and Wales.
Assets that won’t last 2000 years: the practicalities of renewal
© Cammeraydave | Dreamstime.com
ISO 55000 defines asset management as the coordinated activity of an organization to realize value from assets.
I like the word co-ordinated, but I was never so sure about ‘value’.
That AM should be driven by the organizational objectives and targets was defined well before ISO 55000. Physical assets are managed in order to support a company doing what it aims to do, not for their own sake.
If the aims are evil, it follows the asset management isn’t going to be for the angels either.
Not long before it collapsed, I interviewed two Enron asset managers in London. They told me their main job was to know who to bribe and how far you could go before you were thrown in jail. (I suspect they knew the end was near.)
In practice, for many of us, the bigger problem we face is not evil targets, but missing or stupid ones. Organisations don’t know what it is they want their organisation to deliver, other than not making a loss or a scandal. For infrastructure, it surely has to be a service for customers & the community; but how to set meaningful key performance targets for service is often hard work.
Transit has struggled with this forever, but even power generation gets muddled. In markets with shifting prices, what is the amount of electricity we want to produce at any specific time? Apart from anything else, the answer has to involve costs, like spot cost per megawatt, and plenty of power organisations don’t know that. (I’d say rail generally doesn’t have a clue of their cost per passenger mile.)
We default to targets like minimising unplanned outages, because that’s relatively simple. Or even more asset-specific measures like pavement condition index. (Aaargh!)
I am convinced the person who came up with the ISO 55000 definition felt clever – clever to avoid saying ‘lowest cost’ or ‘least risk’. Value is whatever an organisation thinks it is. (And we won’t define ‘asset’ very clearly, either.)
It’s out of scope to discuss where the value comes from or how to capture it in SMART targets.
Quite apart from the evil ones, and our own ethics as asset managers, I believe we have a real challenge with stupid or missing targets. In practice, we cannot just aim to be aligned, if there is nothing that makes sense to align with.
Smart asset managers get drawn into the question of organisational KPIs. I know I was. I think setting meaningful infrastructure targets is closely allied to good AM thinking.
And as for all that missing cost analysis….
Anyone fancy attempting a better definition?
Fire Horse © J2 | Dreamstime.com
We have two problems in current Asset Management. They both need change!
Talking with AM practitioners around the place, one issue is that implementing AM as a system, as in ISO 55000, is not sticking – even if it got somewhere in the first place.
AM is literally nothing if it doesn’t make a fundamental change in how we decide what to do to our existing physical assets.
ISO 55000 is remarkable for not being worse than it is, but – looking back – AM is not primarily a quality management system at all. It’s a radically different way to look at the future.
I now believe that’s where we need to start, not an end point.
And this means going straight to the top, rocking the boat, even burning metaphorical and perhaps even actual bridges.
The second issue is that we really do need to make decisions in a different way: the criteria for appropriate assets have moved on since the 1980s. We cannot continue with assets as usual, in the face of climate change, changing demands, and environmental constraints.
What’s heartening in this Year of the Fire Horse is that growing numbers of asset managers agree, through their frustrations. If it doesn’t shake things up – it’s not Asset Management.
We declare: The Year of the Fiery Platypus. Time to change the rules.
Thank you to Diarmaid O Culain for the inspiration!
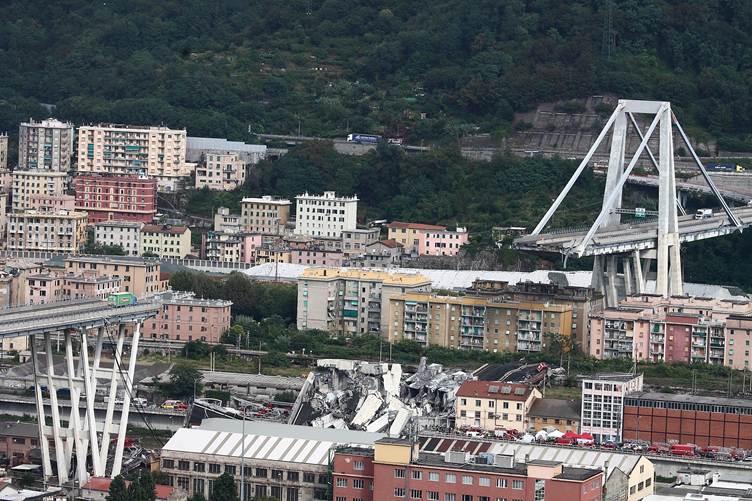
Morandi Bridge Collapse © Valerio Bianchi | Dreamstime.com
The collapse of the Morandi Bridge in Genoa, Italy, in 2018, was a spectacular infrastructure failure. And immediately blamed on lack of maintenance.
43 people died – and now 57 people have been prosecuted for failure to maintain, among other charges.
I was intrigued at the time, because though bridges do collapse, it’s not usually blamed on maintenance. But it is a typical issue for long-life assets, to put off repairs to save money; the point about long-life assets with slow deterioration is that people cross their fingers and hope collapse won’t happen on their watch.
In this case, it appears that nothing was done to address detectable rust in structural steel cables. To see there is rust, and not to act, is if anything even more negligent than not to inspect for rust.
Was it lack of maintenance, or poor design?
I don’t feel much sympathy with the defence argument: those who maintain and operate should surely attempt to understand if there are design issues, and it hardly matters once you can see the rust. (What do you think?)
Charges were laid against engineers, government officials and senior managers. It took almost four years of investigation before the case came to trial, another four years for the trial, and more than 280 hearings. Was it really that technical? I suspect an awful lot of defence buck-passing, and the delay took it beyond their statute of limitations for some of the charges.
This week the former head of the motorway operator was given a 12 year prison sentence, and we can only hope it does encourage the others.
Intriguingly he is already serving a sentence from a separate 2013 road disaster….
© Airam Dato-On – Viewing Vermeer’s Milkmaid
A great book on the importance of maintenance is titled The Innovation Delusion. Asset managers know only too well the ‘dynamic tension’ between building shiny new and keeping our existing systems going.
But a recent book – Peak Human, by Johan Norberg – bangs the drum for innovation in an interesting way. Given one proviso – that we fully acknowledge the horror of human slavery in the past – he suggests we know a golden age when we see one.
“A period with a large number of innovations that revolutionize many fields… in a short period of time.”
Its characteristics, he suggests, are creativity, science, technical achievements, economic growth, better average standard of living. As opposed to stagnation in thought, lack of optimism, lack of tolerance.
The book is a great romp through the usual suspects – Athens, Roman Empire, Renaissance Italy – along with the less familiar, at least to me: Abbasid Caliphate, Song China. The golden age Dutch Republic of trade, non-conformity, great painters, the middle class. The ‘Anglosphere’ from the Industrial Revolution onwards.
Times of curiosity – and a lack of crippling fear of others?
Innovation can’t just mean what the tech-bros say. Revolutionary innovations include doing without kings. With human, women’s and animal rights, and caring for the environment. I am very, very glad we finally understood about germs – and the importance of basic sanitation for everyone.
If innovation Is coming up with better ways of doing things, I am all for it.
But it can’t just be about technology.
- Can we embody a spirit of learning and sharing which isn’t predatory capitalism, instead includes caring for others and sustaining the assets we depend on?
- For feeling in our bones that sustaining is a triumph as much as inventing?
*Happy birthday to my niece Natalie, named in remembrance of the storming of the Bastille this day in 1789
ID 136686433 | Globe © Siarhei Yurchanka | Dreamstime.com
The Institute of Asset Management (IAM) Global Conference June 2026 refreshed me.
It wasn’t just the small but growing community of asset managers who want to discuss (and do) Wave 3 and Wave 4. The conference theme was ‘Connected World – Shaping Our Future’, and several speakers addressed future friendly-infrastructure. Shout out to Miriam MacLennan and Will Adeney for their presentation on regenerative AM, going beyond doing no harm.
It was also refreshingly sophisticated. Not just consultants talking about their projects, unless those projects were instituting Asset Management from scratch at one of the giant airports to be (Jeddah in Saudi Arabia) or managing the M25, nickname The Road to Hell.
Several speakers talked about AI realism – what can it and what can’t it usefully do for AM – and the limits of standards. We cannot afford to be naïve.
There was more discussion off-line about organisations going backwards. One cause is complacency, believing everyone now understands and can do AM, so there’s no need for an AM team. (Let the poachers control themselves?*) On a bad day, I am not sure this is a question of recovery to good Asset Management, so much as proof that some organisations never really understood it in the first place.
There is still work to be done on Wave 2.
But watch out for more on networking around Wave 4!
*From a phrase coined by Jim Kennedy at NSW RailCorp long ago
ID 3723955 | Weaving © Robert Paul Van Beets | Dreamstime.com
I like to think I was searching for Asset Management many years before I heard the term.
This raises a fundamentalist question: what is the deep essence of AM that I sought? Maintenance optimisation, asset data IT, modelling or planning processes: they are all in the mix.
Here’s a link to a Substack-length exploration. Let us know what you think.
Histories of Asset Management: What can we learn from the different strands?
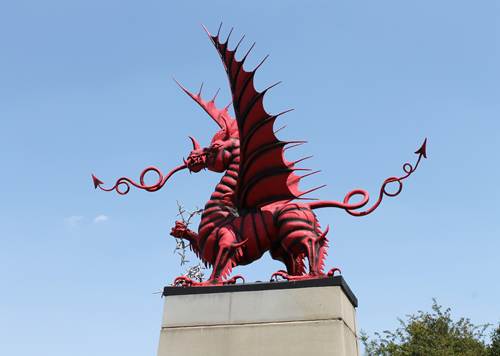
Red Dragon Memorial to 38th (Welsh) Division at Mametz Wood on the Somme, ID 31564612 © Cyclingscot | Dreamstime.com
The previous Welsh government adopted a new focus for its development policies: the foundational economy.
It’s worth quoting from the mission statement.
“The term ‘foundational economy’ refers to the sectors of the economy that provide the goods and services that underpin everyday life.
The foundational economy is more than just infrastructure, employment and output. It is also citizens’ sense of control and belonging in their community. These sectors are by their nature immediate to people’s surroundings, and so they are vital social as well as physical infrastructure.”
Their strategic sectors included both ‘providential’ infrastructure such as social care and health services and more purely physical infrastructure (water & sewerage, energy, transport) plus construction of residential and commercial buildings, food, and ‘high street retail’.
“The foundational economy approach is centred around the Well-being of Future Generations (Wales) Act 2015, which aims to improve the social, economic, environmental, and cultural well-being of Wales.”
Why Wales has turned away from the glam high-tech vision to quality of life… is partly because of the sheer challenge of turning ex industrial communities into Silicon Valley. The latter is a delusion for most economies anyway.
Why foundational economics bundles social care and physical assets together is because they have much in common economically and morally, starting with the base fact that, well, they are at the base of our way of living.
And even physical infrastructure isn’t just a physical service. As they say, it is also about people sense of being in control and “belonging in their community”.
How would it be if such ‘infrastructure’ wasn’t an afterthought but the very heart of our economics?
(And I hope the incoming Plaid Cymru-led government keeps up the good work!)
See Foundational Economy (1922) by the Manchester-centred Foundational Economy Collective. The Welsh Government document can be downloaded from https://www.gov.wales › foundational-economy
In the debate about public versus private ownership of infrastructure, one thing is clear: we don’t need predators.
In the 1980s, some free market entrepreneurs argued that we should design policy and society to give free rein for what they called predators – themselves, in other words – to predate.
And then their predatory eyes fell on physical infrastructure.
Having already asset-stripped manufacturing companies, they need fresh blood. And this time we were all the prey.
We depended on adequate government regulation, but predatory thinking infested our governments.
We can fog this with talk of efficiency, innovation, managing public debt and use of private capital, but ‘extractive predation’* is much snappier.
*From Foundational Economy (2022)
See also Hettie O’Brien, The Asset Class: How Private Equity Turned Capitalism Against Itself (2026)
When UK councils were encouraged to develop Asset Management Plans (AMP) in the early 2000s, local government advisors had to warn them off cutting and pasting other councils’ plans.
It is perhaps hard to think of a worse way to plan – to misunderstand what an AMP is all about. Any two councils will have different portfolios of assets, even for similar services. Different types, different ages.
How to plan for asset renewals using shared heuristics with similar organisations might have been a useful conversation.
But even if councils try to write their own plan, they can fail to use them: I love Ashley Bishop’s comment that “often the only thing that comes out an AMP is the dead spider when you open it”.
And so many organisations have struggled with the process – or rather, failing to see that planning is a business process. And a key one, not a one-off document written by someone at a desk, even if they are an Asset Manager who works for the council..
The problem is, this is so fundamental to Asset Management. That asset planning is a way of life embedded into core business as usual.
That not planning is the very problem we are trying to solve.
So, although in general I would support any regulatory requirements to do an AMP, we have to face the real paradigm shift.
How can you take responsibility for vital infrastructure assets, and not look ahead?
How did we get here?
Recent Comments